My name is Dorothy Mitchell, and at seventy years old, I learned the difference between generosity and surrender while standing barefoot in the snow outside my own son’s house.
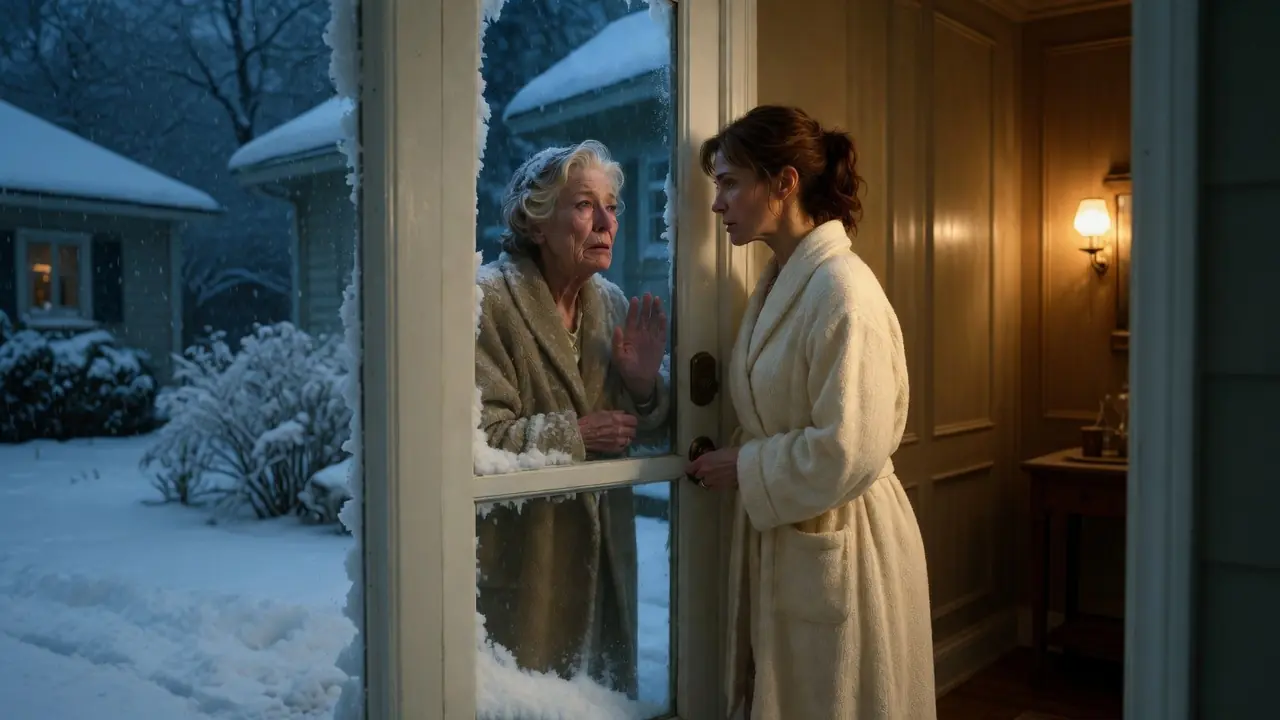
It was 2:00 a.m. in Minneapolis, the kind of February night when the cold did not simply touch your skin, it entered your bones and made a home there. Snow blew sideways across the porch steps, gathering in the corners of the railing and whitening the welcome mat I had bought for Michael and Rebecca five Christmases earlier. Through the locked glass storm door, I could see the warm hallway light glowing behind my daughter-in-law’s shoulder.
Rebecca Mitchell stood inside the house in her cream knit robe, one hand still near the deadbolt. I stood outside in a wool coat thrown over my nightgown, shaking so hard my teeth hurt. Tears ran down my face, turning cold almost as soon as they reached my cheeks.
“Rebecca,” I said, pressing one trembling hand against the glass. “Please open the door. I am freezing.”
She looked at me as if I were a disobedient child who had finally earned a punishment. Behind her, deeper in the hallway, my son Michael stood half-hidden near the staircase. He did not step forward. He did not reach for the lock.
Rebecca leaned toward the glass and said, “Maybe this will teach you not to interfere with our family decisions.”
Then she turned away from the door.
For a few seconds, I did not understand what had happened. My mind refused to accept it. I had paid for that house’s down payment. I had paid for the twins’ private school, their vacations, their tutoring, their activities, their emergency expenses, and half the lifestyle Rebecca loved to display online. Yet there I was, locked outside in a storm by people who had spent years calling me family whenever they needed money.
I knocked again. “Michael,” I called, my voice cracking. “The door is locked.”
He did not answer.
The hallway light blurred through my tears. Snow gathered on my slippers. The wind cut through my nightgown and slipped under my coat like icy fingers. At that moment, as I stared at the door my son refused to open, every excuse I had ever made for him and Rebecca fell apart.
I had spent two years believing I was helping my family. The truth was colder than the porch beneath my feet.
I had been funding my own exploitation.
For thirty-eight years, I had been Dorothy Mitchell, founder and CEO of Mitchell Financial Services, one of the most respected independent wealth management firms in the upper Midwest. I built that company from nothing after my husband Paul died in a car accident at thirty-five, leaving me with a three-year-old son and ten thousand dollars from my grandmother. I invested carefully, worked relentlessly, and learned early that money was not security unless you understood how to protect it.
My first client was myself. I turned that small inheritance into fifty thousand dollars within eighteen months through careful stock selections and bond investments. People at church and in the neighborhood began asking for advice. What started as informal guidance became a consulting practice, then a registered investment advisory firm, and eventually a company managing hundreds of millions in client assets.
I did not merely manage other people’s money. I built my own fortune with the same discipline I preached. I invested in commercial real estate in downtown Minneapolis before the area revived. I bought rental properties in growing suburbs. I put money into software and medical technology companies before they became major players in the Minneapolis-St. Paul business corridor.
By my seventieth birthday, my personal net worth had reached eighteen million dollars, not including the full value of my company or several trust structures I had established over the years. I owned a penthouse overlooking the Mississippi River, a lake house on Gull Lake, and an investment portfolio that generated approximately eighty-five thousand dollars per month in passive income. Dividends, rental income, bond interest, and partnership profits flowed into my accounts whether I was working, sleeping, or foolishly funding people who had mistaken kindness for weakness.
They knew I was comfortable. They knew I had money. But they did not understand that a woman who had built an eighteen-million-dollar fortune had also learned how to spot predators, structure protection, and cut off access when generosity turned into abuse.
For years, Michael had been charming but inconsistent. As a child, he was bright, creative, and full of ideas, but he struggled whenever effort had to continue beyond excitement. He started neighborhood newspapers, lawn-care services, photography projects, music lessons, and art hobbies, each one abandoned when the work became tedious.
I funded his explorations because I loved him. I told myself he was finding his path. When he switched college majors several times and took six years to finish with a general studies degree, I paid every bill and praised his persistence. When he quit jobs after a few months because customers were unreasonable, supervisors were unimaginative, or the work did not allow creativity, I gave him a soft place to land.
Looking back, I see what I could not see then. I had removed too many consequences. When Michael walked away from responsibility, he never met the full weight of his choices. He met his mother’s open door, his mother’s checkbook, and his mother’s belief that one more chance would finally make him steady.
When he met Rebecca, I thought everything would change.
She was twenty-five then, a nursing graduate from the University of Minnesota, practical, hardworking, and seemingly devoted to Michael. She came from a middle-class family in Duluth and spoke about budgeting, responsibility, and building a stable home. During their engagement, she helped Michael stay at a job longer than usual, encouraged him to set financial goals, and appeared to understand everything he lacked.
I paid for their wedding at the Guthrie Theater, a thirty-five-thousand-dollar celebration with river views, a seven-course dinner, live music, premium drinks, and flowers that transformed the venue into something from a magazine. Rebecca cried when she saw the room. Michael hugged me and said he would make me proud.
Six months later, I gave them forty thousand dollars for a down payment on a modest four-bedroom colonial in Minnetonka. With Rebecca earning sixty-five thousand as a nurse and Michael earning forty-eight thousand as a property manager, they could manage the mortgage and build a responsible life. For the first year, that seemed to happen.
Then Emma and Jacob were born.
The twins were beautiful, healthy, and loved from the moment they entered the world. Emma was alert and curious, studying everyone around her as if collecting secrets. Jacob was calmer, more observant, the kind of baby who watched before deciding whether the world was worth reacting to.
I opened college savings accounts for each child with twenty-five thousand dollars apiece. I babysat several evenings a week. I bought cribs, car seats, strollers, toddler beds, clothes, toys, and little educational sets that matched their personalities. When Emma showed interest in music, I bought a small piano and arranged lessons. When Jacob loved building blocks and simple machines, I bought construction sets and early engineering toys.
When Rebecca reduced her nursing schedule to part-time after the twins were born, I understood. Twins are exhausting. I contributed fifteen thousand dollars that first year to help with daycare, medical bills, clothing, and the general increase in household expenses.
By the time the twins were three, I was giving Michael and Rebecca roughly twenty-five thousand dollars a year in support. It was no longer just emergencies or special gifts. It was regular help, expected help, help that had quietly become part of their budget.
I told myself it was fine because I could afford it.
The first serious warning came when Emma and Jacob reached kindergarten age. Their neighborhood public school was strong, diverse, well-funded, and perfectly capable of giving them a good education. But Rebecca had toured St. Catherine’s Academy and decided the twins needed smaller classes and more individualized attention.
“It’s really an investment in their future,” Rebecca told me during Sunday dinner. “Instead of buying them toys they’ll outgrow, we could invest in something that helps them for life.”
The school cost nine thousand dollars per year per child.
Eighteen thousand dollars annually.
I agreed because I loved my grandchildren and believed in education. But in doing so, I created a precedent. From that point forward, if Michael and Rebecca decided something was “good for the children,” I was expected to pay for it.
Then Michael left property management to pursue real estate sales. He explained that his old job was steady but did not offer “unlimited growth.” Rebecca said they only needed help during the transition. Licensing, training, marketing, clothing, a professional car lease, and living expenses during the first lean months added up to forty-five thousand dollars over eighteen months.
Michael promised he would pay me back once commissions became consistent.
He never did.
After eighteen months, his real estate career brought in about thirty-five thousand dollars a year, less than his old salary. But instead of admitting the move had failed financially, Michael and Rebecca called it “building momentum” and continued relying on me to bridge the gap.
Their lifestyle inflated quickly. Emma’s piano lessons became piano, voice coaching, dance, and art. Jacob’s interest in building became robotics, programming camp, advanced math tutoring, and science competitions. Their activities alone cost around twelve hundred dollars a month.
Vacations became annual expectations. Disney World. A Caribbean cruise. A Colorado ski trip. Each one cost thousands. Each one was called family bonding, childhood memories, or emotional enrichment. Rebecca documented everything on her family blog, carefully presenting an image of success they could not afford.
The way they asked for help changed too.
At first, there were requests. Then announcements. Rebecca would say, “Dorothy, I registered Emma for the advanced dance intensive. The fee is twenty-eight hundred dollars, and she needs new outfits and shoes.” Michael would say, “Mom, I put a deposit on the Colorado ski condo. The total will be about eleven thousand, but it will be amazing for the kids.”
They made decisions first and informed me afterward. If I hesitated, I became the person disappointing the children.
By the time the twins were ten, I was funding about eighty-five thousand dollars a year beyond what Michael and Rebecca could afford. Private school, mortgage help, utilities, insurance, activities, vacations, clothing, technology, tutoring, and household expenses. They were living an upper-middle-class lifestyle on a middle-class income, and my money held the whole illusion together.
Then Rebecca proposed what she called a “family financial optimization meeting.”
She had spreadsheets, printed articles, and a presentation prepared. She wanted regular monthly transfers, joint accounts for family expenses, education trusts, automatic payments, and formal structures that would make my support predictable and harder to withdraw. She called it smarter money management.
My financial adviser called it what it was.
A transfer of control.
“Dorothy,” he told me, “these arrangements would convert your voluntary gifts into practical obligations. The tax benefits are modest. The access benefits for Michael and Rebecca are substantial.”
I refused.
That refusal changed everything.
They became subtler. They began using guilt. Emma asked why she could not go to Disney like her friends. Jacob asked why I would not buy him a three-hundred-dollar robotics kit when I had so much money. The children were not being cruel on their own. They were repeating what they had been taught.
Then came the isolation.
Rebecca said my bridge nights seemed too tiring. Michael suggested I step back from charity boards because younger people could handle the burden. They discouraged consulting work, international travel, and even my art and wine collections by framing everything as concern for my age and safety.
My friend Margaret noticed before I did. “Dorothy,” she said one evening, “are you sure they’re worried about your well-being, or are they controlling your time?”
I dismissed her then.
I should not have.
By the winter of 2024, Michael and Rebecca had positioned themselves as the main voices in my life. They monitored my schedule, filtered invitations, answered calls, collected mail, and spoke as if my financial decisions were family decisions. They tried to push me toward estate planning that would transfer control of assets to younger family members “in case my capacity changed.”
My capacity had not changed.
Their patience had.
The final confrontation began during a brutal February blizzard. My penthouse building was undergoing heating repairs, so Michael and Rebecca insisted I stay with them for a few days. I thought they were being kind. In truth, I believe now they were testing how much control they could exert with me under their roof.
That night, after dinner, I was reading in the living room while Michael and Rebecca cleaned the kitchen. The twins were upstairs doing homework. I heard their voices at first but did not listen until Rebecca grew sharper.
“She’s being completely unreasonable about estate planning,” Rebecca said. “We’ve given her so many chances to do the right thing for the family.”
Michael answered with a tired resentment I had never heard from him before. “She has more money than she could spend in three lifetimes, but she acts like helping her own family is a burden.”
I froze.
Then Rebecca lowered her voice and said, “Maybe it’s time to have a serious conversation about Dorothy’s living situation.”
Michael asked what she meant.
Rebecca said the house was crowded, that I was becoming harder to manage, and that perhaps assisted living or a senior community would be better. She said I was showing signs of cognitive decline. She said professional care might help me develop a more appropriate perspective about money, management, and family responsibility.
I stood slowly.
My son and daughter-in-law were discussing how to put me away, not because I needed care, but because I had refused to hand them control of my money.
I walked into the kitchen.
“I heard you,” I said.
They both turned white.
Rebecca tried to smile. “Dorothy, you misunderstood. We were just discussing contingency planning.”
“No,” I said. “You were discussing how to get rid of me because I am inconvenient and because I will not give you the financial control you want.”
Michael started to speak, but I stopped him.
“I heard exactly what you said. You think I’m selfish. You think I’m difficult to manage. You think I belong in professional care because I won’t agree to your estate schemes.”
Rebecca’s embarrassment hardened into anger.
“You know what, Dorothy?” she said. “Maybe it is time for honesty. You are seventy years old. You live alone in a huge penthouse. You resist practical planning. You act like supporting your family is some outrageous imposition.”
“My money is not your entitlement,” I said.
She laughed coldly. “When you have wealth and your family needs support, helping is not charity. It is obligation.”
There it was.
The belief beneath every request, every manipulation, every guilt trip.
My wealth was not mine. It was theirs, and I was selfish for controlling it.
“So what exactly are you proposing?” I asked.
Rebecca looked at Michael, then back at me. “We are proposing that you start acting like a responsible family member instead of a selfish old woman who cares more about controlling money than caring for people.”
The words struck like a slap.
“And if I don’t?” I asked.
“Then maybe you should decide whether you want to be part of this family or apart from it,” Rebecca said.
That was the threat. Submit financially, or lose access to my son and grandchildren.
I looked at them both and felt something inside me turn calm.
“You are absolutely right,” I said. “This arrangement is not working for everyone. I need to decide whether I want to be part of this family dynamic or apart from it.”
I put on my coat and stepped outside onto the porch to think. The cold hit me so hard I gasped. Behind me, Michael called that we could discuss it reasonably, but I stayed where I was, facing the snow-covered street.
After ten minutes, I was ready to come back inside.
The door was locked.
I knocked. “Michael, the door is locked.”
No answer.
I knocked harder. “Rebecca, let me in. It is freezing out here.”
Then Rebecca appeared behind the glass and delivered the sentence I will never forget.
“Maybe this will teach you not to interfere with our family decisions.”
She walked away.
I stood there shaking, tears freezing on my face, realizing my son and daughter-in-law were willing to risk my life to prove they controlled me.
That was when I stopped being sad.
I became clear.
I walked to my car through the snow and drove back to my penthouse in the most dangerous drive of my life. By the time I reached the warmth of my own home, I was numb, trembling, and absolutely certain.
At 3:00 a.m., I called Margaret.
She arrived with her daughter Linda, a nurse practitioner, who documented my condition, photographed the frostbite on my fingers, and wrote a statement about my physical and mental clarity. Margaret documented everything I told her. I wanted witnesses before I acted.
Then I called my attorney, James Harrison.
“James,” I said, “I need immediate legal action to protect myself from financial elder abuse before business hours.”
I told him everything. The manipulation, the isolation, the estate pressure, the assisted living conversation, and the locked door.
“What you are describing is elder abuse and financial exploitation,” he said. “Possibly endangerment as well.”
“I want restraining orders,” I said. “But first, I want every credit card, bank account, automatic payment, and financial privilege connected to Michael and Rebecca frozen immediately.”
Then I called my financial adviser, Robert Chen.
“Robert,” I said, “every account with secondary access for Michael or Rebecca needs to be locked down. Every card canceled. Every automatic payment stopped. Every authorization revoked.”
He was quiet for a moment. “Dorothy, this will affect their mortgage, utilities, school payments, activity fees, and household expenses.”
“That is exactly what I want,” I said. “They just locked me outside in a blizzard because I would not give them more control over my money. Tomorrow they will learn what happens when they lose the control they already had.”
By 6:00 a.m., everything was in motion.
By 9:00 a.m., while Michael and Rebecca were getting the twins ready for school, my attorney served them with restraining orders, and my financial adviser canceled their access to my resources. Credit cards tied to my accounts were declined. Household checking access was revoked. Automatic payments stopped. Legal authorizations for financial and medical matters were terminated.
At 10:00 a.m., Michael began calling.
At 11:00, Rebecca called from another number.
By noon, their voicemails had turned frantic.
“Mom, there’s been a mistake with the credit cards,” Michael said. “Can you call the bank?”
“Dorothy,” Rebecca said later, “the checking account says access has been revoked. We have bills due today.”
By 2:00 p.m., Michael sounded panicked. “The mortgage payment is due tomorrow. We can’t access anything. Please call us back.”
By 4:00 p.m., Rebecca’s voice had turned cold again. “If you do not restore access, we will pursue legal action. You cannot use money as a weapon against your own family.”
That evening, the police came to my penthouse because Michael and Rebecca had reported that I was experiencing confusion and making irrational financial decisions.
I showed the officer Linda’s medical documentation, Margaret’s witness statement, the photographs of my injuries, and the restraining orders.
The officer’s expression changed as he listened.
“Ma’am,” he said carefully, “are you saying your family members caused these injuries?”
“I am saying my son and daughter-in-law locked me outside in subzero weather because I refused to give them control over my financial accounts.”
He closed his notebook slowly. “Would you like to file charges?”
“Yes,” I said. “I think it is appropriate.”
Over the next several weeks, Michael and Rebecca faced the truth of their own finances for the first time. Without my money, they could not pay the mortgage on time. They received utility warnings, private school notices, activity cancellations, and vehicle payment threats. Their lifestyle collapsed because it had never belonged to them.
Rebecca had left nursing to become a full-time household manager and family blogger. Michael’s real estate income was only about thirty-five thousand dollars a year. They had been living as if they earned far more because I had funded the difference.
During mediation, Michael pleaded with me.
“Mom, you are destroying our family over one argument.”
“This is not one argument,” I said. “This is two years of financial exploitation that escalated into locking me outside in life-threatening weather.”
Rebecca tried a more calculated approach. “The children should not suffer because of adult conflict.”
“The children are suffering because their parents chose to live beyond their means,” I answered, “then used that dependence to control and abuse the person paying for it.”
After six weeks, Michael and Rebecca finally admitted they had taken advantage of my generosity. Rebecca apologized for locking me out, though I could not tell whether it was remorse or strategy. Michael seemed more broken, more ashamed, and perhaps more honest than I had seen him in years.
They wanted to rebuild.
I gave them terms.
No financial support until trust was rebuilt and sustained. No requests, no expectations, no assumptions. No involvement in my financial decisions, estate planning, professional advisers, or legal documents. No using the twins as leverage. No threats, no manipulation, no intimidation.
“If anything like that night ever happens again,” I told them, “there will be no mediation. There will only be permanent consequences.”
Six months later, our family looked different.
Rebecca returned to full-time nursing and earned seventy-five thousand dollars a year. Michael began treating real estate as an actual career and increased his income to sixty-five thousand. Together, they made enough to live modestly without my subsidies.
The twins moved to public school and adjusted better than anyone expected. Emma joined the school dance team, which cost two hundred dollars a semester instead of thousands. Jacob joined the school robotics club, where he learned to build with limited resources instead of expecting expensive equipment to solve every problem.
Most importantly, they started treating me as a person again.
“Grandma Dorothy,” Emma asked one evening, “can you tell me how you started your company after Grandpa Paul died?”
Jacob asked if I would teach him about investing because he wanted to be financially independent one day.
Those conversations meant more than any expensive vacation I had ever funded.
Two years have passed since that frozen night. I am seventy-two now, active, independent, and surrounded again by friends who had worried for me long before I admitted I needed help. I still give gifts when I choose. I still contribute to the twins’ college accounts. But every gift is voluntary, and every boundary is clear.
I no longer confuse love with access.
I no longer confuse generosity with obligation.
Michael once told me that cutting off their access to my money was the best thing that ever happened to his marriage and family. I believe him. Not because it excused what they did, but because consequences forced them to become people my money had prevented them from becoming.
The frozen bank accounts were not revenge.
They were education.
And the night they left me outside in the cold became the night I finally stopped paying for people who could not keep a door open for me.